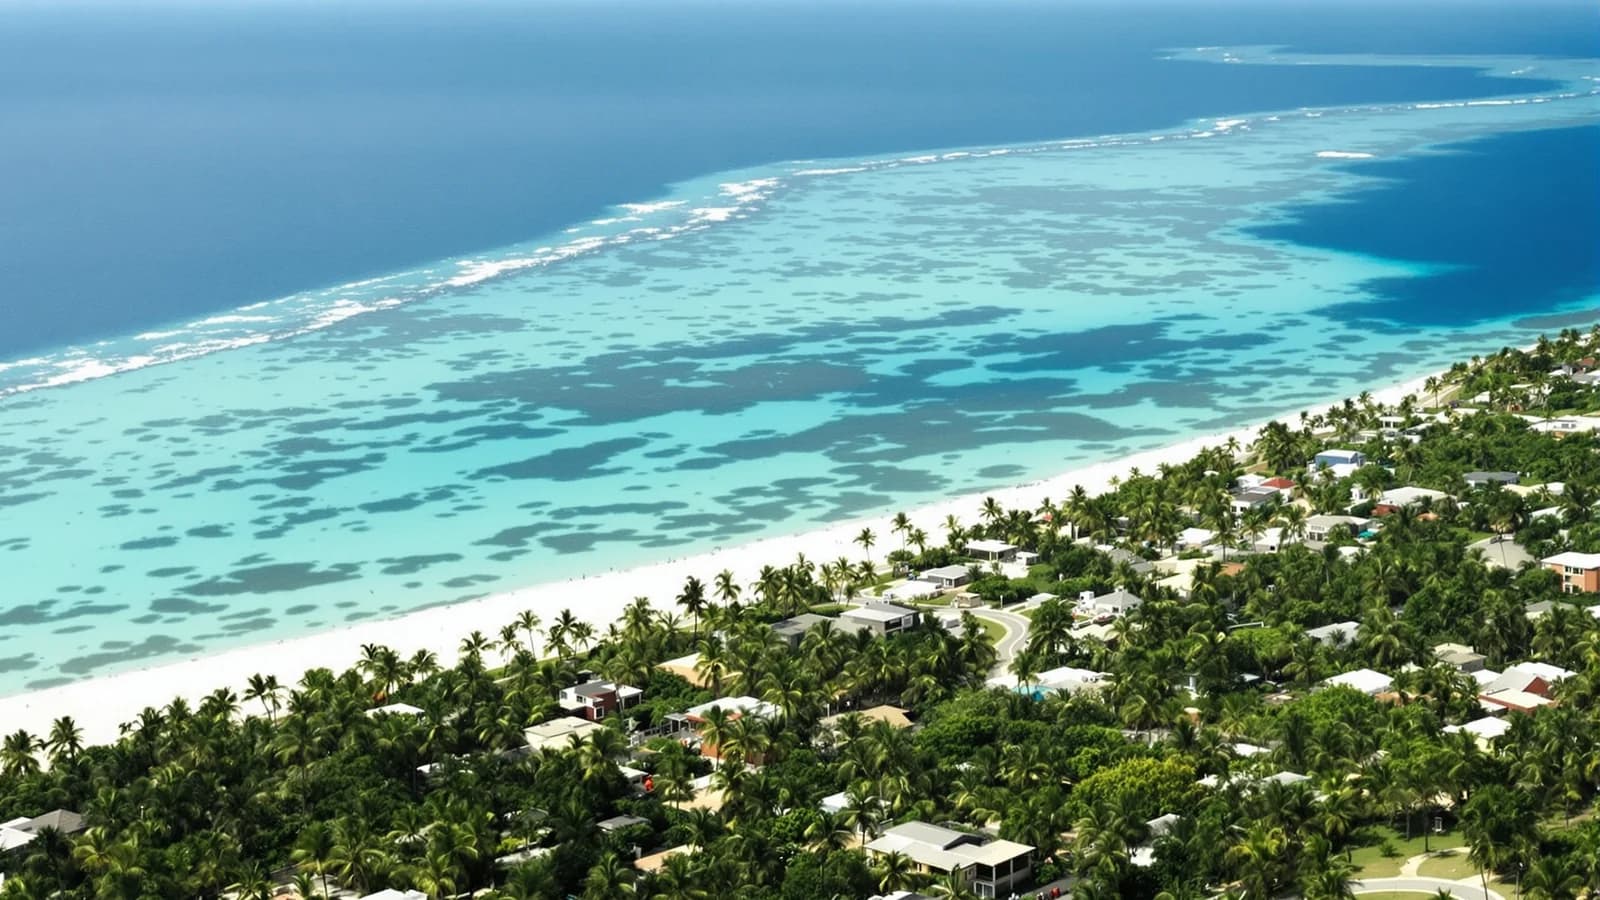

There is a moment that comes up again and again in consultations about Mexico. Someone has fallen in love with a house on the Riviera Maya, a flat in Puerto Vallarta or a plot in Baja California, and then somebody by the pool tells them: "As a foreigner you can't own anything here, it all belongs to the bank." Then they call me, half alarmed, half angry. Neither is necessary. Put like that, the claim is wrong, but there is truth at its core, and that is exactly what you need to understand before you put down a single peso.
So, one thing at a time: why you cannot simply go onto the property register on Mexico's coasts, how the fideicomiso really works, what it costs, where the real traps are, and what to make of the reform rumours of 2026.
Why the restricted zone exists at all
Article 27 of the Mexican Constitution of 1917 bars foreigners from acquiring direct ownership of land within a strip of 100 kilometres along the country's borders and 50 kilometres along its coasts. This is the so-called zona restringida, the restricted zone. The historical background is not harassment of today's buyers but a trauma: in the 19th century Mexico had lost half of its territory to the United States, and the revolutionary constitution wanted to keep strategic border and coastal strips permanently in Mexican hands.
In practice: Mexico City, Guadalajara, Querétaro, San Miguel de Allende and Mérida lie outside the zone, and there you are registered as owner in your own name like anyone else, whatever your nationality. But almost everything people dream of when they think of Mexico lies inside the zone: the entire Riviera Maya with Playa del Carmen and Tulum, Cancún, Los Cabos, Puerto Vallarta, the whole Pacific and Caribbean coast. If you want to buy there, you need one of the two permitted structures. For residential property it is practically always the fideicomiso.
What the fideicomiso really is, and what it is not
The fideicomiso is a bank trust under Mexico's Foreign Investment Law of 1993. A Mexican bank is formally entered on the property register as trustee, the fiduciaria. You are the fideicomisario, the beneficiary, and you hold every economic right to the property: you may live in it, let it, renovate it, mortgage it, sell it and leave it to your heirs. The bank may do nothing with the property that you do not instruct it to do. It is the custodian of title, not the owner in any economic sense, and your claim is ring-fenced from the bank's assets in an insolvency.
I always clear up two misunderstandings at this point. First: the fideicomiso is not a lease and not a "leasehold" as in parts of Asia. You buy the full economic value, and when you sell, you pocket the full appreciation. Second: the maximum term of 50 years is not a ticking clock after which your house falls to the state. Article 13 of the Foreign Investment Law expressly provides that the term is extended on application, again by up to 50 years, as often as you like. In practice the extension is an administrative step, not a new purchase. The structure has been in use since the 1970s, was put into its present statutory form in 1993, and is handled routinely by banks, notaries and courts. It is the official, court-proof route, not a loophole.
I compare buying through a trust with owning in your own name in more depth in the article on owning property in your own name in Latin America. Mexico is the special case there, and a well-functioning one.
The process step by step
This is how a purchase in the restricted zone runs in practice, from handshake to keys:
Step 1: Preliminary contract and deposit. You agree terms with the seller and sign a promesa de compraventa, a private preliminary contract with the price, deadlines and withdrawal clauses. A deposit of 5% to 10% is usual. My urgent advice from experience: pay only into escrow, never directly to the seller or agent, before the title check is complete. The most common mishap buyers report in the Riviera Maya expat forums is exactly this: paying first and checking afterwards.
Step 2: Choose a bank as trustee. You instruct a Mexican bank to set up the fideicomiso. Active providers include Banorte, Scotiabank, Monex, Actinver and Multiva. Terms differ noticeably, both the set-up fee and the annual fee, so it pays to get two or three quotes. Your local notary or attorney usually has established contacts.
Step 3: Foreign Ministry permit. The bank applies for a permit for the fideicomiso from the Secretaría de Relaciones Exteriores, Mexico's Ministry of Foreign Affairs. The application runs electronically through the SIPAC system, contains details of you, the bank, the property and its intended use, and should officially be decided within five working days. That deadline, however, has been suspended for years because of system problems; in reality it often takes several weeks. For ordinary residential purchases the permit is not a substantive risk; it is normally granted. In the process you sign the so-called Calvo Clause: you undertake not to ask your home government to intervene in matters concerning this property. It sounds more dramatic than it is, and has been standard since 1917.
Step 4: Title check by the notary. In Mexico the notario público is a state-appointed lawyer with an official duty to verify, with far more authority than a notary in the United States, and to be taken as seriously as a civil-law notary in Europe. The notary obtains the certificado de libertad de gravamen, proof that the property is free of encumbrances, checks the chain of ownership, outstanding property taxes and development levies, and has an official valuation prepared. Because the notary does not represent either party, experienced buyers also hire their own attorney, entirely independent of the seller. With six-figure sums, that is not paranoia but standard practice.
Step 5: Completion. Once the permit and checks are through, the notary executes the escritura pública, the public deed of sale, in which the fideicomiso is created at the same time. The purchase price is released from escrow, the deed is entered in the Registro Público, and you get the keys. From preliminary contract to registration you should realistically allow two to four months.
For what happens on the tax side after the purchase, from the low predial property tax to capital gains tax on a sale, I have written a separate detailed guide: buying property in Mexico. The international summary of Mexican taxes comes from PwC.
What it all costs
Now for the numbers, unvarnished. The government permit fee for the fideicomiso under the fees law, the Ley Federal de Derechos, is just over 21,600 pesos in 2026, roughly EUR 1,000, plus a small review fee; it is adjusted every year. The bank typically charges USD 500 to 1,500 to set up the trust, depending on the institution. Add up the permit, the bank fee and the associated handling costs, and at completion you usually end up at USD 2,000 to 3,000 for the fideicomiso structure alone. On top comes the bank's annual fee, currently in the region of USD 500 to 800, up to USD 1,000 at some institutions.
These items come on top of the normal purchase costs, that is notary, property transfer tax, registration and valuation, which in Mexico add up to around 5% to 8% of the purchase price depending on the state. My rule of thumb for coastal purchases: budget the transaction costs as you would for a purchase in Europe, plus a low four-figure sum once and a mid three-figure sum each year for the trust. Anyone whose USD 300,000 purchase founders on a USD 700 annual fee should rethink the project anyway.
A practical note on the banking landscape that matters more in 2026 than any fee table: CIBanco, for years the largest trust provider, was named by the US Financial Crimes Enforcement Network (FinCEN) in June 2025 over money-laundering concerns and was then taken over by the Mexican authorities. Its entire trust business, with thousands of fideicomisos, was transferred to Multiva, and the takeover was approved by the authorities at the end of 2025. Legally, nothing changed for existing fideicomisos; the contracts continue with the new trustee. But the episode shows two things. First, the structure survives even the failure of the largest trust bank; that is exactly what the insolvency ring-fencing is for. Second, when choosing a bank today you should not simply take what the agent suggests, but compare fees, responsiveness and stability.
The alternative: a Mexican company, but not for living in
There is a second legal route into the restricted zone: a Mexican corporation whose articles admit foreign shareholders. Under Article 10 of the Foreign Investment Law, such a company may acquire property in the zone directly and merely has to notify the Ministry of Foreign Affairs of the purchase within 60 working days. The catch sellers like to leave out: this only applies to non-residential purposes, that is hotels, rental businesses, commercial use and development projects. Holding your private beach house through a company set up specially to avoid the fideicomiso defeats the purpose, and it saddles you with ongoing bookkeeping, tax and reporting obligations that are more expensive and more tiresome than any trust fee. For genuine investors with several rental properties, on the other hand, the company can be the right structure. That is a calculation to be done case by case, ideally before the first preliminary contract is signed.
Ejido land: the trap that ruins lives
And so to the most important section of this article. A considerable share of Mexico's land is ejido land, communal agricultural land from the land reform after the revolution. Ejido parcels are not on the ordinary property register; they belong to the community, and they simply cannot be validly sold to foreigners unless they have been privatised and properly titled in a lengthy formal procedure. Yet exactly this kind of land is offered on the Riviera Maya, around Tulum and on up-and-coming stretches of the Pacific coast, often 30% to 50% below market price, often with the line that privatisation is "already under way", sometimes even with notarised-looking papers covering mere rights of use.
Never buy anything like this. Not with an attorney, not at a discount, not because the neighbour did it too. The community assembly can annul such sales, courts declare them void, and attorneys in Tulum report a steady stream of foreign buyers who, years later, stand with worthless papers in front of a house that never belonged to them. In these cases there is no tidy way to unwind the deal and no title insurance that covers it. The rule that protects you is simple and absolute: a property for which no unbroken private chain of ownership up to the escritura pública in the Registro Público can be shown does not exist for you as a buyer. On Mexico's coasts, a price that looks too good is not a bargain; it is a warning sign.
Inheritance in a fideicomiso: the underrated advantage
One point that rarely comes up in sales conversations but regularly tips the balance in my consultations: in the fideicomiso contract you name one or more sustitutos, substitute beneficiaries, from the outset. If the primary beneficiary dies, they step into the beneficiary position by virtue of the contract, without Mexican probate, without a court, without months of limbo in a foreign legal system. The bank checks the death certificate, and the trust is transferred. Anyone who has ever been through a foreign probate procedure knows what this clause is worth. With direct ownership outside the restricted zone you need a Mexican will for this; in the fideicomiso, succession is built in. Still, name the substitute beneficiaries carefully and keep them up to date, including after divorces and new additions to the family. A forgotten sustituto cancels out the advantage.
The 2026 reform rumours: what is verified and what is not
Since the Sheinbaum government took office, two opposing rumours have regularly been doing the rounds in forums and agents' newsletters: the restricted zone is about to be abolished and foreigners will soon be able to buy directly. Or the reverse: foreigners will be banned from buying on the coast altogether, in response to the gentrification protests. The verifiable position in August 2026 is unspectacular: there is no enacted reform that abolishes, replaces or tightens the fideicomiso. The most serious attempt so far to open Article 27 to foreigners was passed by the Chamber of Deputies in 2013 and then fizzled out in the Senate, ironically in the face of opposition from the party that governs today. The gentrification debate of 2025 led to rent measures in Mexico City, not to changes in property law for the coastal zone. What really changes every year are the indexed government fees, and what really shifted in 2025 is the trust-bank landscape after the CIBanco case. Anyone who tells you that you must "buy quickly before the reform" or "better not buy at all because of the reform" is selling you urgency in both cases, not the legal position.
Who it makes sense for, and who it doesn't
Finally, the honest assessment I give every client. As a Plan B building block, a Mexican coastal property in a fideicomiso is a sound proposition: a proven legal structure, full economic rights, built-in succession, and a country where, with residency, you can live without a day counter, and whose everyday life I have described in the guide moving to Mexico. The trust costs are the price of legal certainty in the most beautiful locations in the country, and it is a fair one.
As a pure yield investment I would scrutinise the same property more strictly. Transaction costs are higher than for a direct purchase inland, holiday letting on the Riviera Maya has become more competitive, tax on resale needs planning from day one, and the annual bank fee eats noticeably into returns on smaller properties. If investment is your main aim, lay the company route, locations outside the restricted zone and the overall tax burden side by side before you let the sea view dictate the numbers.
If you are seriously looking to buy on the Mexican coast and want to know whether a fideicomiso or a company fits your case, how to set up the title check properly and how the purchase fits into your residence and tax planning, talk to us before you sign the preliminary contract. We look at your property, your structure and your Plan B together, clear-eyed and without the salesperson's rose-tinted glasses.
👉 Book a consultation with Harley
Carpe Diem. Life is short and fleeting. One shot. Make it count.